Can the Nasdaq be fine while Europe struggles?

A fictional story exploring another perspective

Consider how fiscal stress originating in France reaches the Nasdaq, and the conditions that could limit its impact.

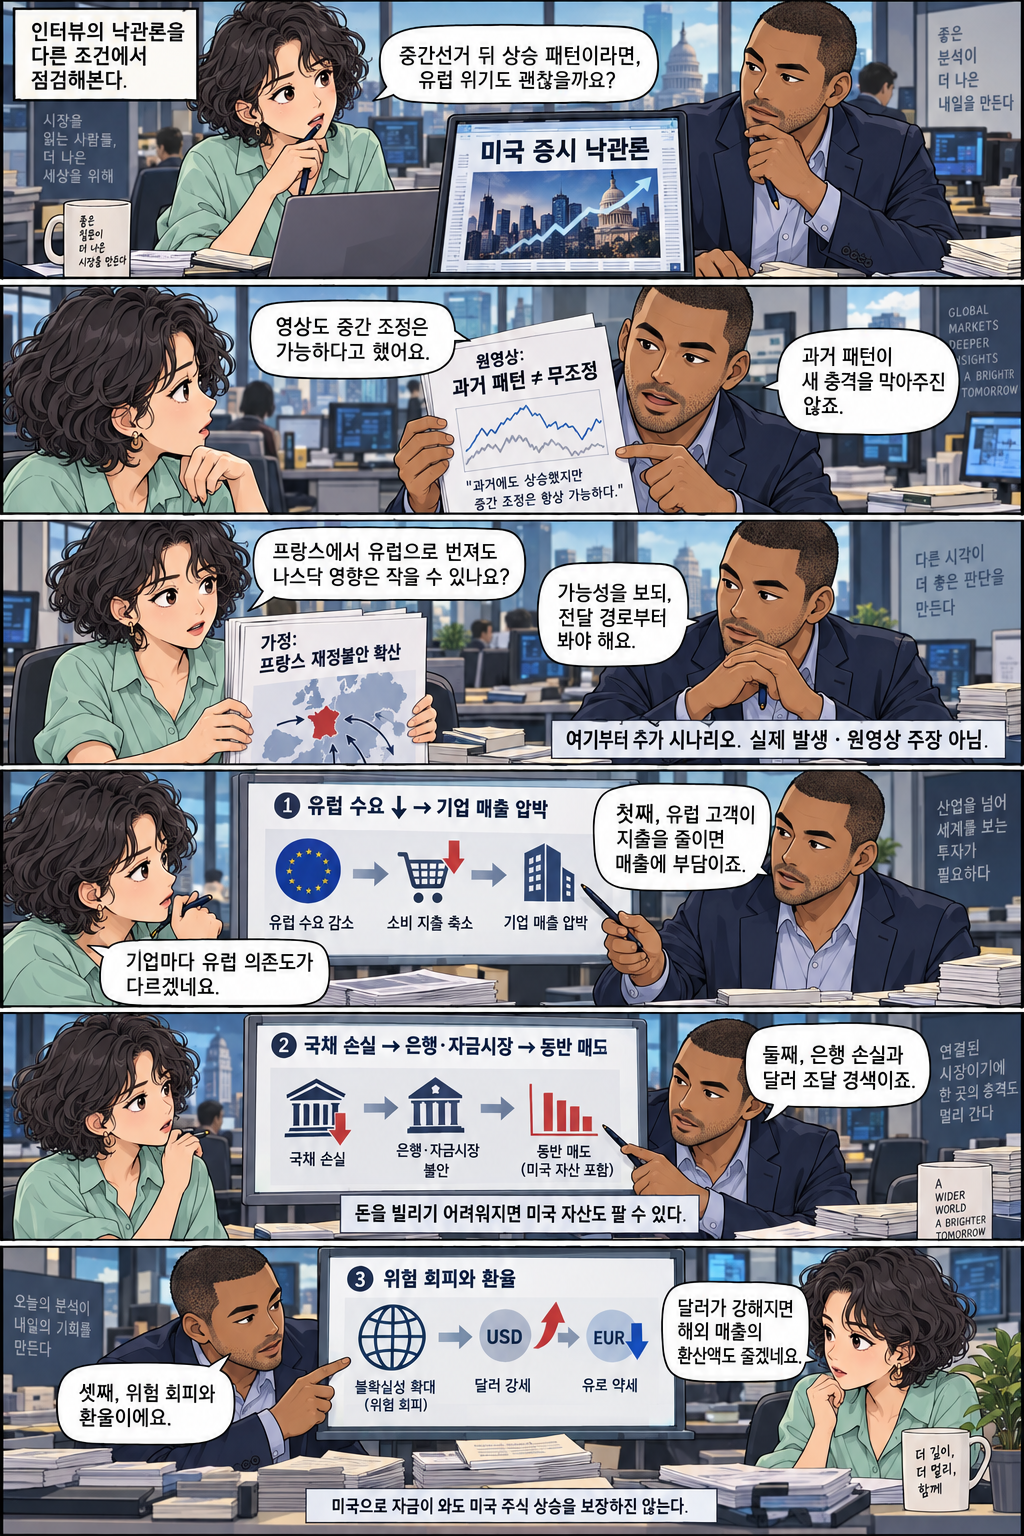
Six panels in which reporter Yuna and analyst Leo examine the video’s optimism, then explain how hypothetical French fiscal stress can spread through US company sales, banks, dollar funding, and exchange rates.
Dialogue

If stocks have risen after midterm elections, will a European crisis be fine too? The video also allowed for corrections along the way. Past patterns do not block new shocks. Could France’s troubles spread across Europe yet barely affect the Nasdaq? It is a possibility, but start with transmission channels. The following is an additional scenario—not an actual event or claim from the original video. First, less spending by European customers can weigh on sales. Companies have different dependence on Europe. Second, bank losses and tighter dollar funding. If borrowing becomes difficult, US assets may be sold too. Third, risk aversion and exchange rates. A stronger dollar also reduces translated foreign revenue. Money flowing into the US does not guarantee rising US stocks.
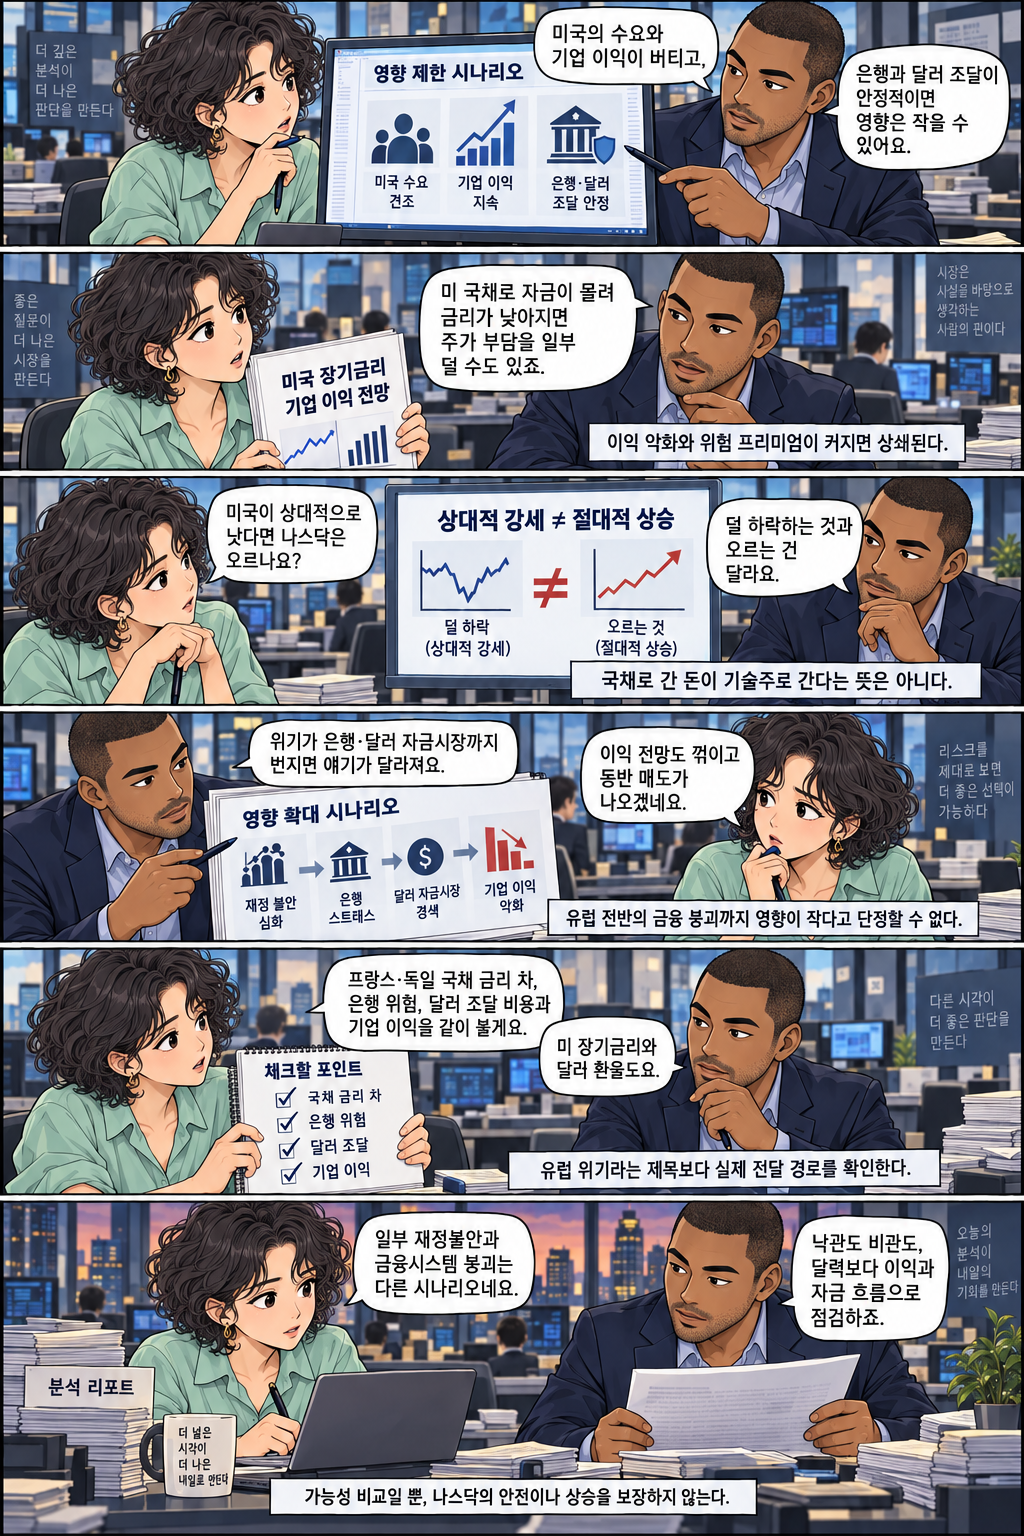
Six panels comparing indicators to check, relative strength versus absolute gains, and the possibility of limited effects if US demand, corporate earnings, and funding hold up—while distinguishing widespread financial collapse.
Dialogue

The impact could be small if US demand and earnings hold up, and banks and dollar funding remain stable. Money moving into US Treasuries and lowering yields could also ease some pressure on stocks. Weaker earnings and higher risk premiums can offset that. If the US does relatively better, will the Nasdaq rise? Falling less and rising are different. Money entering Treasuries does not necessarily enter technology stocks. It is a different story if the crisis reaches banks and dollar funding markets. Earnings expectations could weaken and simultaneous selling could follow. We cannot assume a Europe-wide financial collapse has little impact. I will track the French–German sovereign yield gap, bank risks, dollar funding costs, and corporate earnings together. And long-term US yields and dollar exchange rates. Limited fiscal stress and financial-system collapse are different scenarios. Test optimism and pessimism through earnings and funding flows, not the calendar. This compares possibilities; it does not guarantee Nasdaq safety or gains.

ASSETCASTING commentary

An interpretation of the fictional story, not a statement by the original video creator.

The first two panels express the past rally pattern and possibility of interim corrections discussed at 11–163 seconds in original dialogue, not direct quotations. French fiscal stress is an additional assumption requested by the user, not a video statement or an actual event. The Fed’s 2023 report is used only as support for transmission channels from foreign shocks to the US, not as evidence of a current crisis or Nasdaq returns. Fictional people and scenes are distinguished from independent analysis of exchange-rate and sales channels.

Limited and amplified effects are independent conditional scenarios, not probabilities or predicted returns. The limited-impact scenario assumes US demand and earnings hold up, and banks and dollar funding markets remain stable. The potential discount-rate benefit of Treasury inflows and falling yields can be offset by weaker earnings and higher risk premiums. It does not generalize that a Europe-wide financial collapse would have negligible effects. This compares transmission channels and falsification conditions, rather than recommending trades or promising rising prices.

Story references

Was this helpful?