Rates and stocks both rising: who is wrong?

A fictional story exploring another perspective

Distinguish credit warnings from a stock-market collapse, and consider interest rates, earnings, and concentration together.

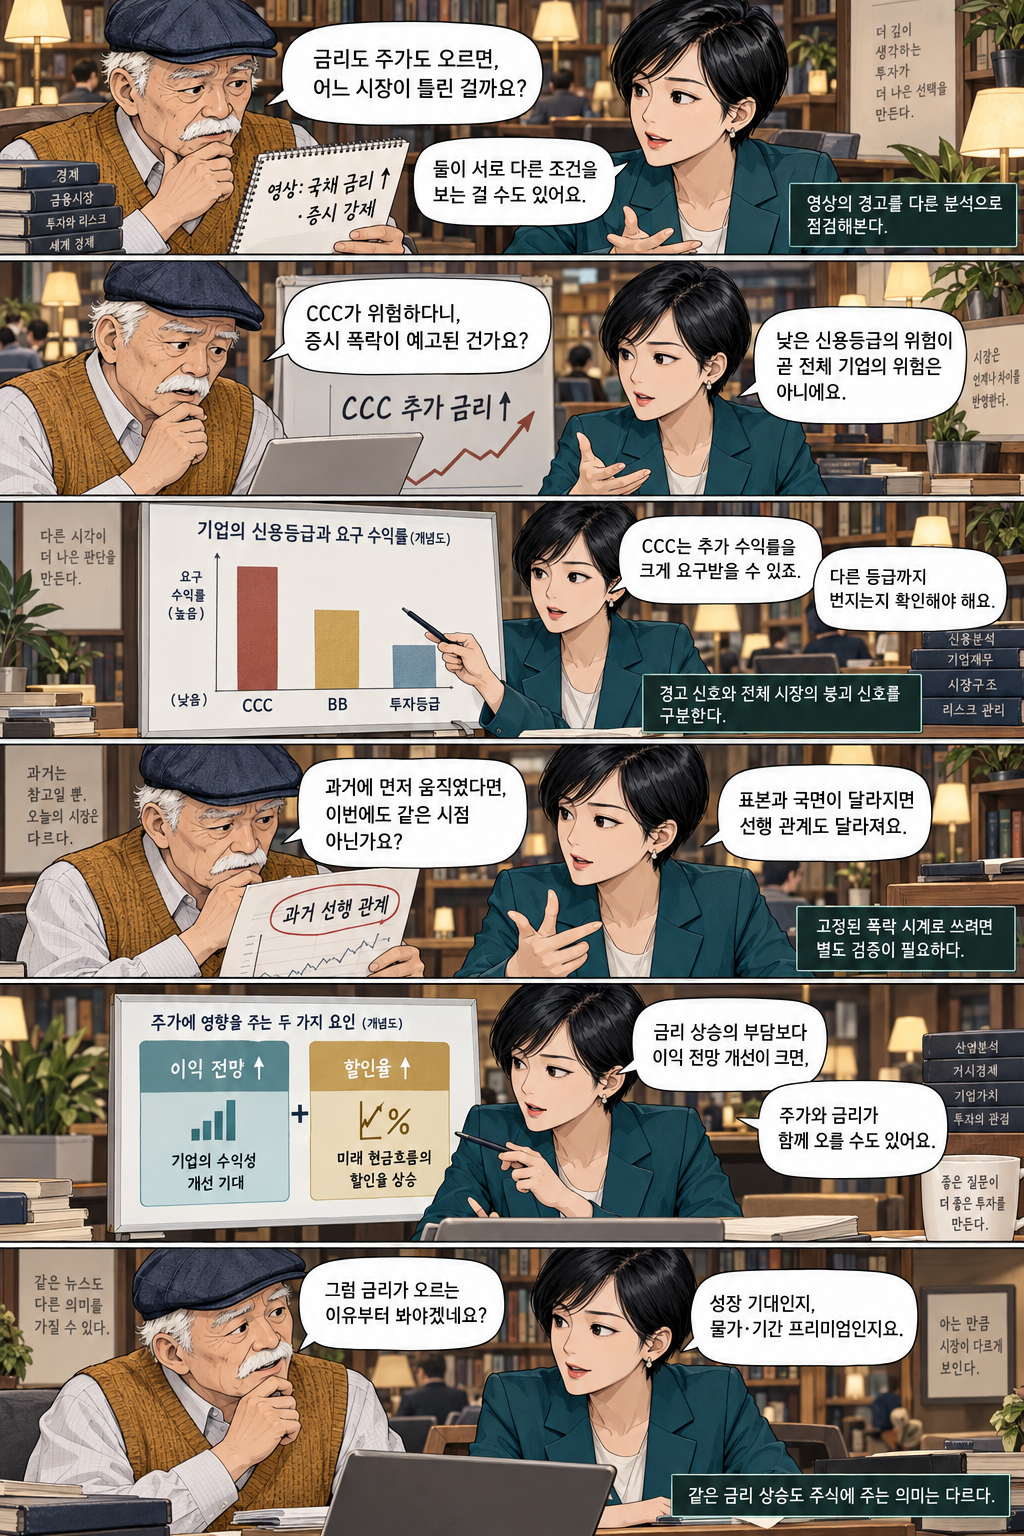
Six panels in which Jae-ho and Eun-seo distinguish risks in CCC spreads from a broad stock-market crash, examining limits of leading relationships, earnings expectations versus discount rates, and reasons for rising rates.
Dialogue

If rates and stocks both rise, which market is wrong? They may be looking at different conditions. If CCC is risky, does it signal a stock-market crash? Risk among low-rated borrowers is not automatically risk across all companies. CCC borrowers can face demands for much higher additional yields. Check whether it spreads to other ratings. Distinguish warning signals from signs of a whole-market collapse. If it moved first in the past, will the timing match again? Different samples and regimes can change the leading relationship. Using it as a fixed crash clock requires separate validation. Stocks and rates can rise together if improving earnings expectations outweigh the burden of higher rates. Then we should first ask why rates are rising? Growth expectations, or inflation and the term premium? The same rate increase can mean different things for equities.
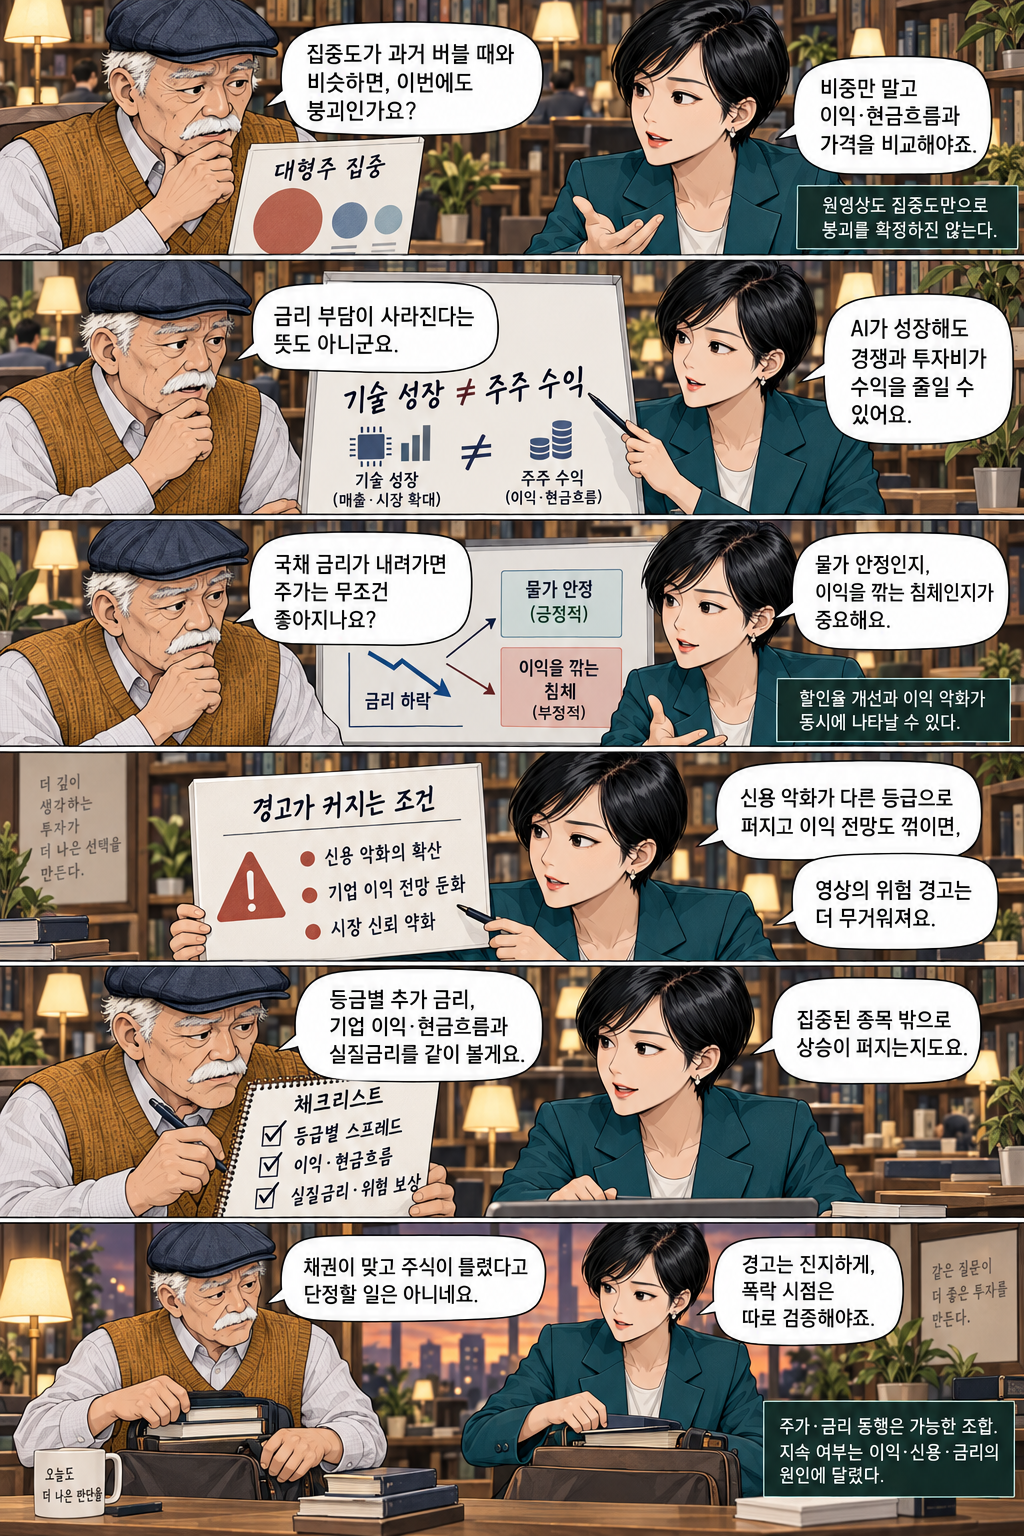
Six panels explaining limits of market concentration, technology growth versus investment returns, different reasons for falling rates, conditions that strengthen credit warnings, and indicators to check.
Dialogue

If concentration resembles a past bubble, will there be a collapse again? Compare earnings, cash flows, and prices—not just weights. The original video also does not establish a collapse from concentration alone. Even if AI grows, competition and investment spending can reduce returns. It does not mean interest-rate burdens vanish either. Are falling government-bond yields always good for stocks? It matters whether inflation is stabilizing or a recession is hurting earnings. Better discount rates and weaker earnings can coexist. If credit deterioration spreads to other ratings and earnings forecasts weaken, the video’s risk warning becomes more serious. I will examine spreads by rating, corporate earnings, cash flow, and real interest rates together. And whether gains broaden beyond the concentrated stocks. We cannot simply say bonds are right and stocks are wrong. Take warnings seriously, but validate crash timing separately. Stocks and yields rising together is possible. Its persistence depends on earnings, credit, and the causes of rate movements.

ASSETCASTING commentary

An interpretation of the fictional story, not a statement by the original video creator.

The counterargument targets expanding the video’s warning into a fixed crash prediction. The video acknowledges that broader high-yield spreads beyond CCC are not all widening and presents three scenarios. This is preserved while distinguishing low-rated credit risk from risk across all companies, and historical leading relationships from verified prediction. FRED is used only to check the scope and definition of the CCC-and-below indicator; licensed figures, time series, and graphs are not reproduced. Illustrations are original conceptual diagrams without numbers. Fed concepts of earnings and discount rates are distinguished from independent conditional analysis. Current rate and concentration figures from the original video are not reproduced without independent verification.

At 109–210 seconds, the original video also does not establish a collapse from a concentration threshold alone. The webtoon adds independent analysis that company groupings, profitability, and prices must be compared across eras. It distinguishes technological growth from shareholder returns, and falling rates caused by stabilizing inflation from those caused by recession. It also provides falsification conditions: credit deterioration spreading to other ratings and worsening earnings forecasts strengthen the video’s warning. No current improvement in results, disappearance of risks, stock-price gains, or crash timing is claimed, and this is not investment advice. Illustrations, characters, and dialogue are original creations.

Story references

Was this helpful?