
Dialogue
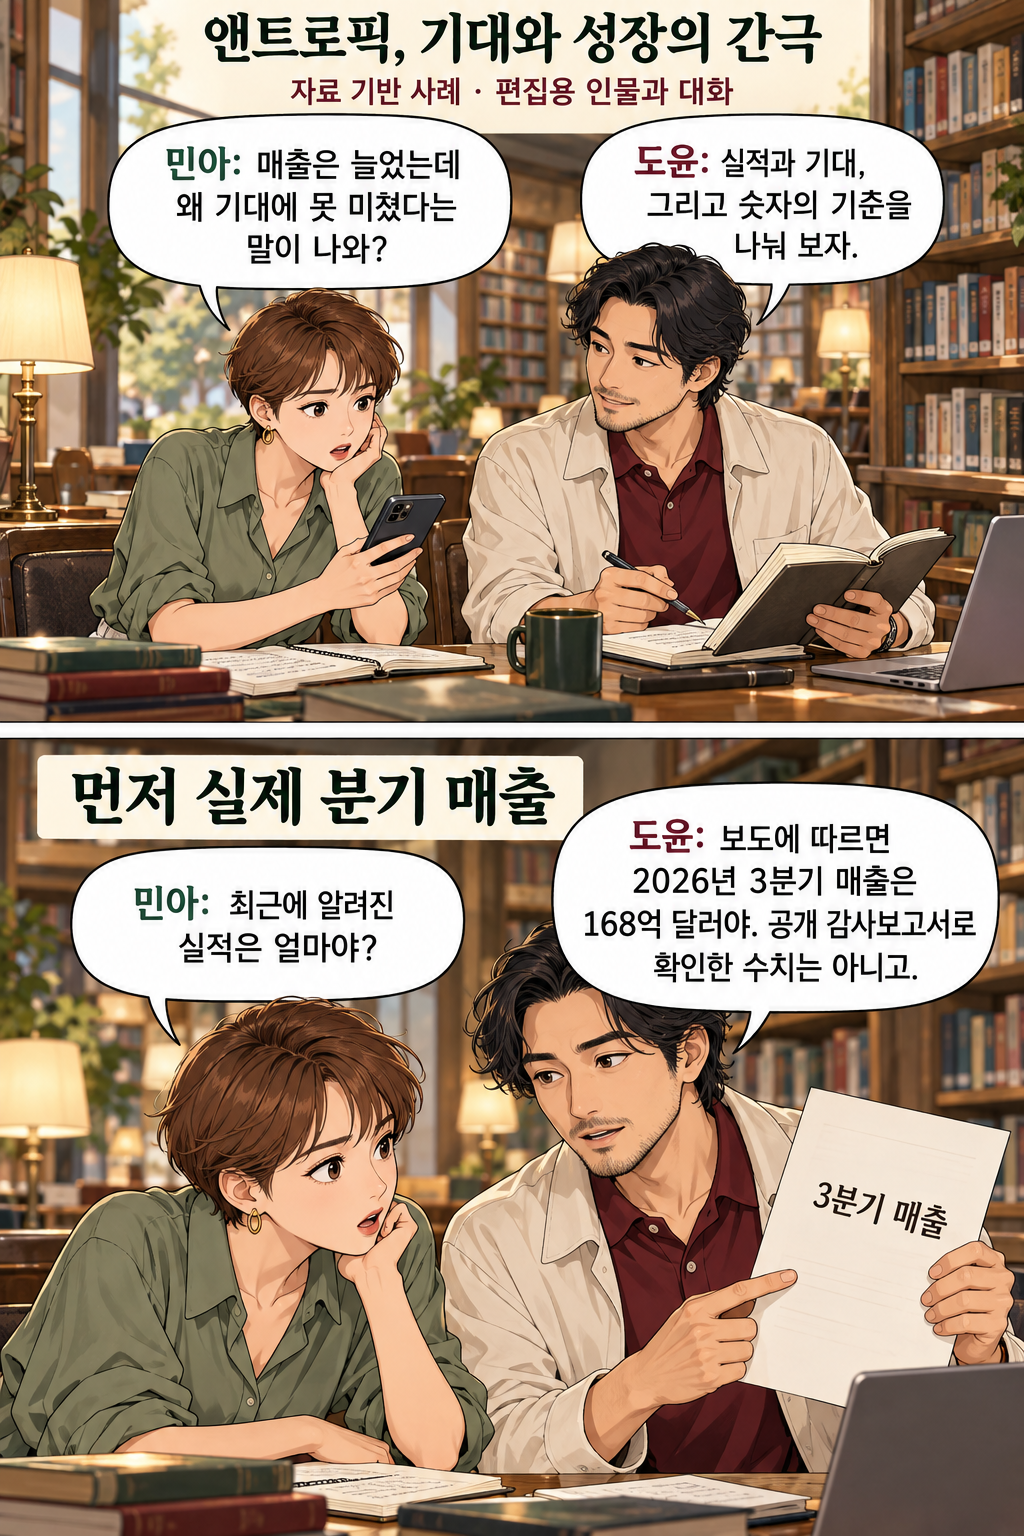
Anthropic: The Gap Between Expectations and Growth Source-based case · Editorial characters and dialogue Mina: Revenue grew, so why do people say it fell short of expectations? Doyun: Let's separate results, expectations and what the figures measure. First, actual quarterly revenue Mina: What are the latest reported results? Doyun: According to reports, revenue for quarter 3 of 2026 was 168 hundred million dollars. We did not verify it through a public audited report.
Dialogue
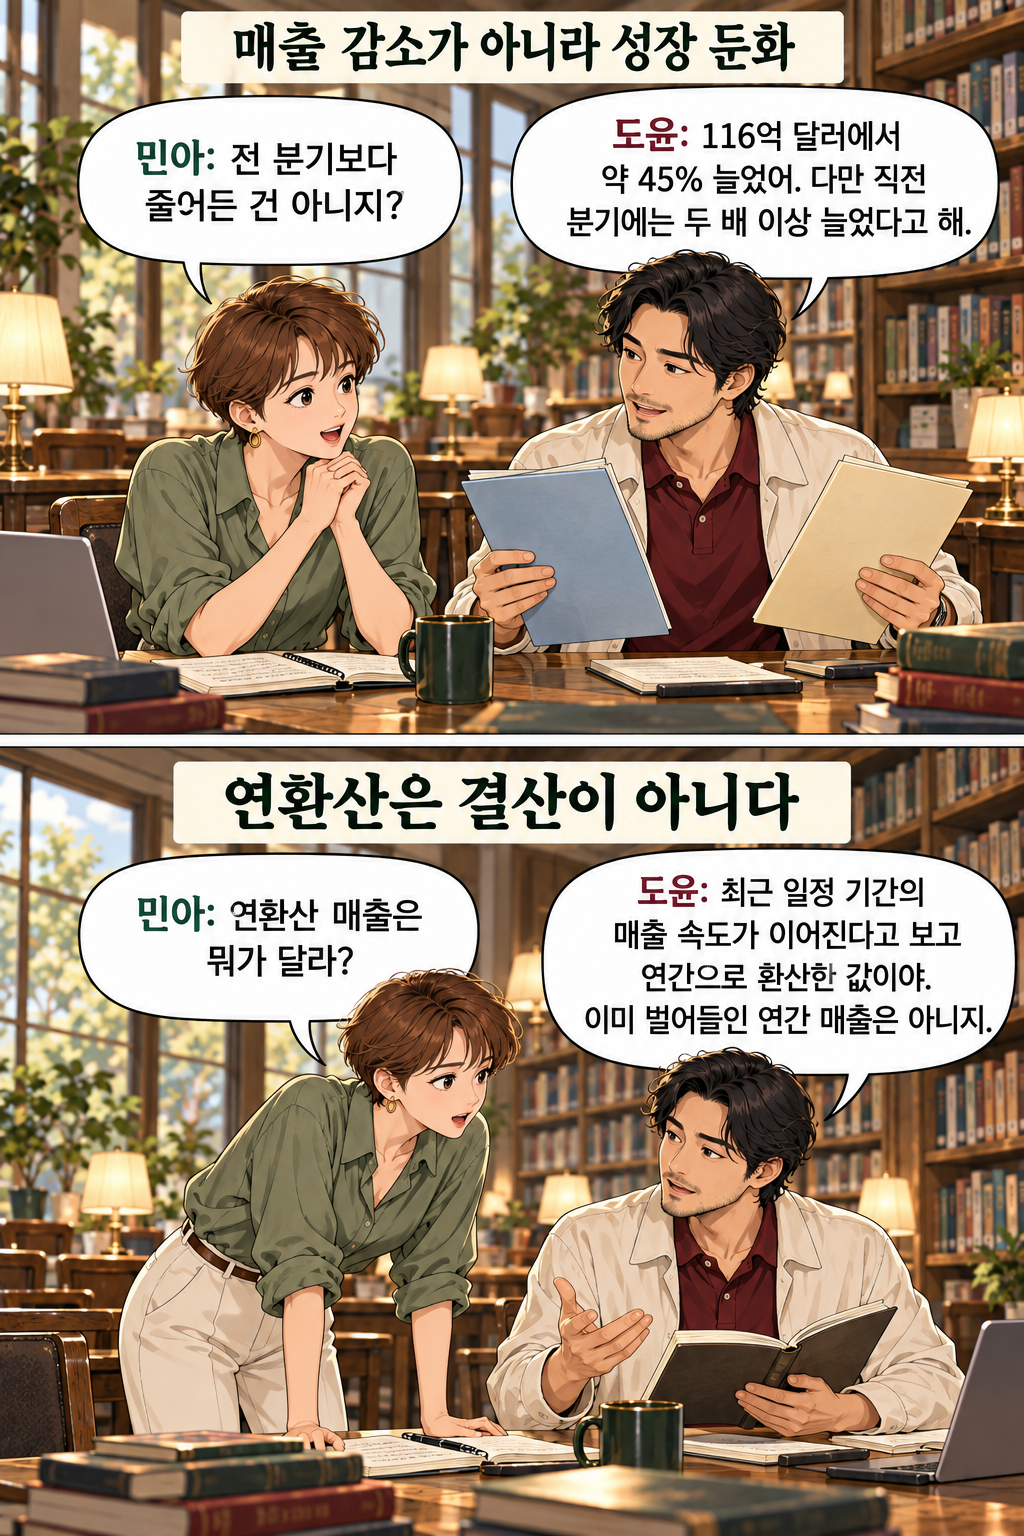
Slower growth, not falling revenue Mina: It did not decline from the previous quarter, right? Doyun: It increased by about 45% from 116 hundred million dollars. But revenue reportedly more than doubled in the preceding quarter. Annualization is not a year-end account Mina: How is annualized revenue different? Doyun: It extrapolates a recent period's revenue pace over a year. It is not full-year revenue already earned.
Dialogue
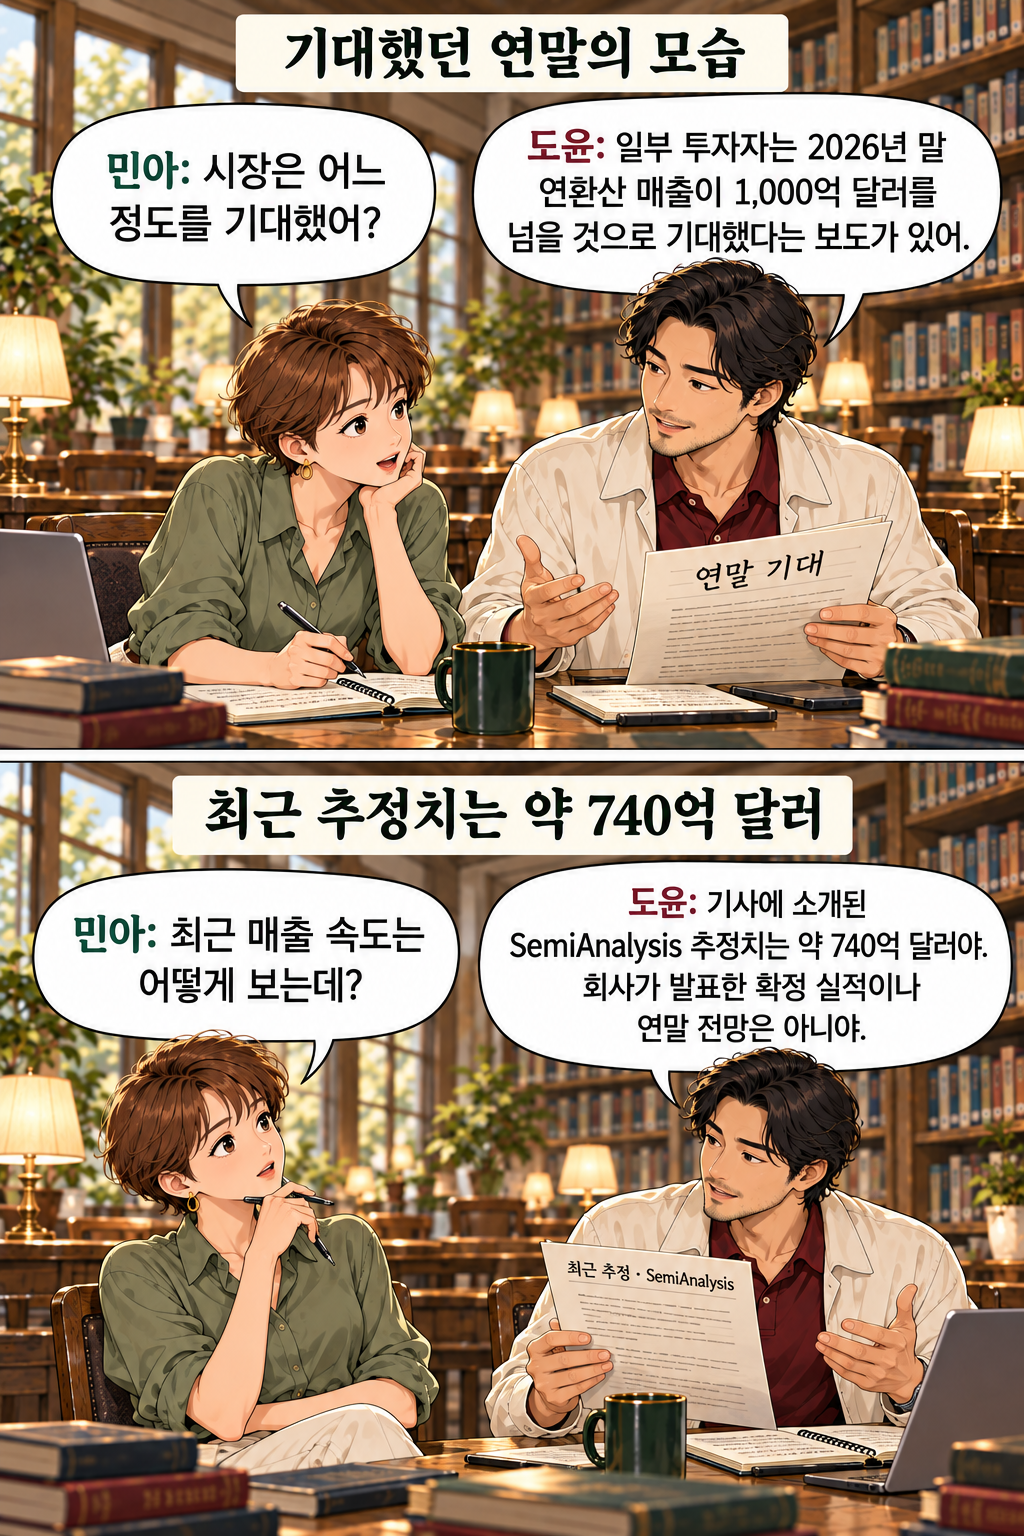
The year-end picture investors expected Mina: What did the market expect? Doyun: Reports say some investors expected annualized revenue to exceed 1,000 hundred million dollars by the end of 2026. The recent estimate is about 740 hundred million dollars Mina: What is the recent revenue pace estimated to be? Doyun: The SemiAnalysis estimate described in the article is about 740 hundred million dollars. It is not confirmed company results or official year-end guidance.
Dialogue
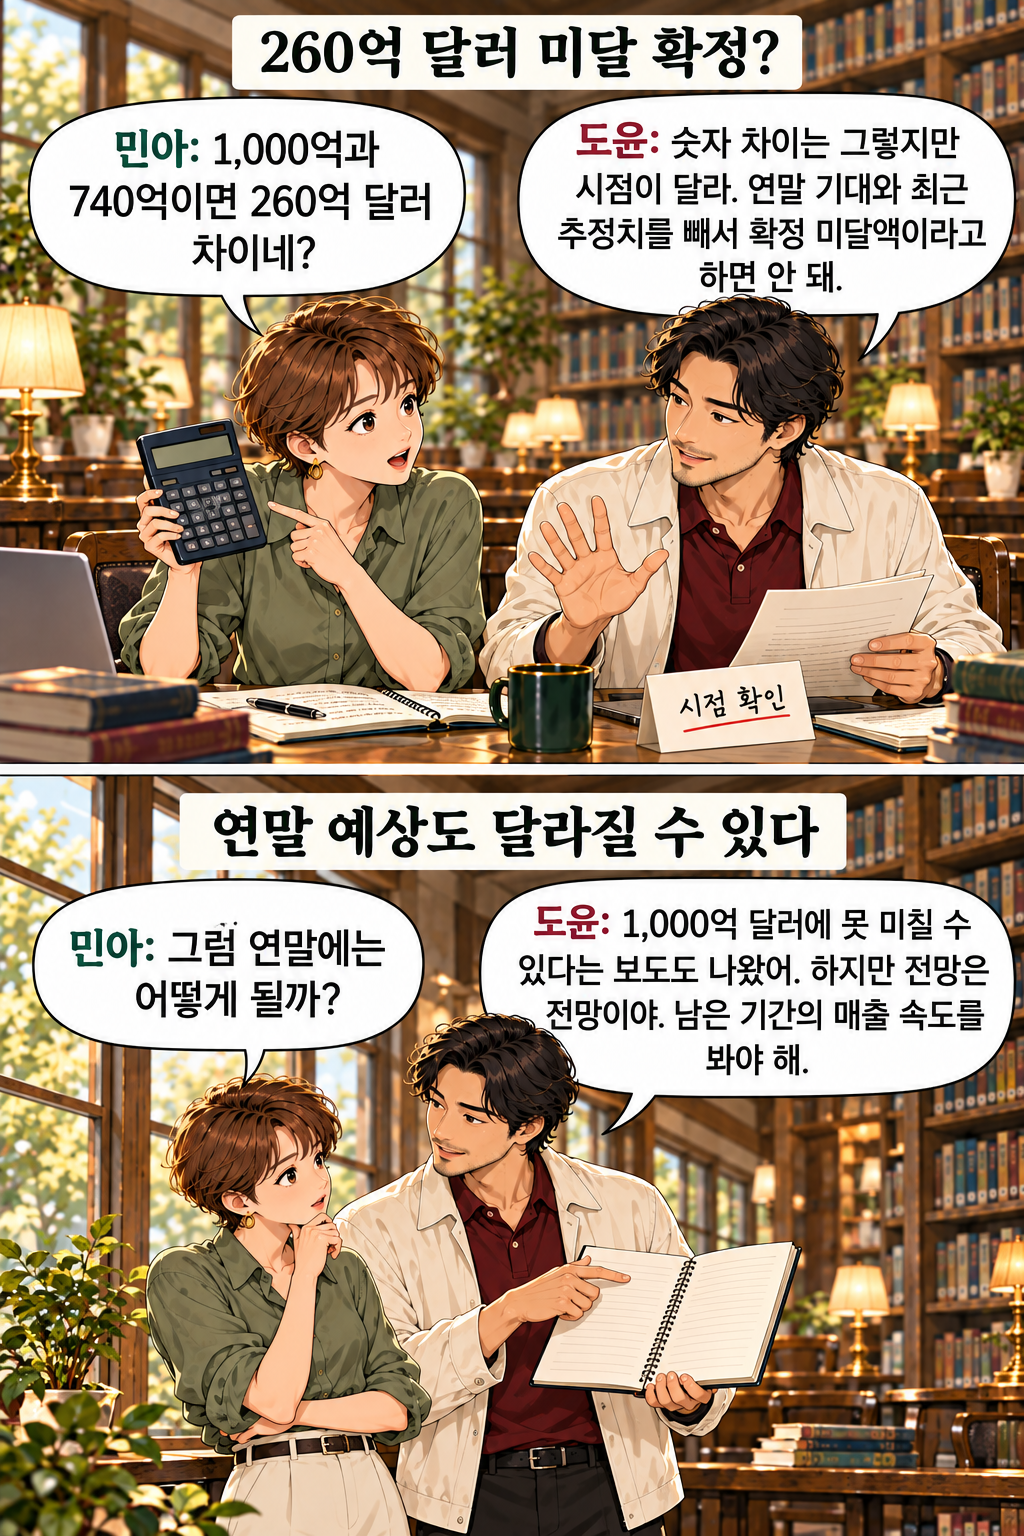
A confirmed shortfall of 260 hundred million dollars? Mina: The difference between 1,000 and 740 hundred million is 260 hundred million dollars! Doyun: That is the numerical difference, but the dates differ. Subtracting a recent estimate from year-end expectations does not establish a confirmed shortfall. Year-end forecasts can change too Mina: What will happen by year-end, then? Doyun: Reports also suggest it could fall short of 1,000 hundred million dollars. But a forecast is a forecast. We need to observe the revenue pace over the remaining period.
Dialogue
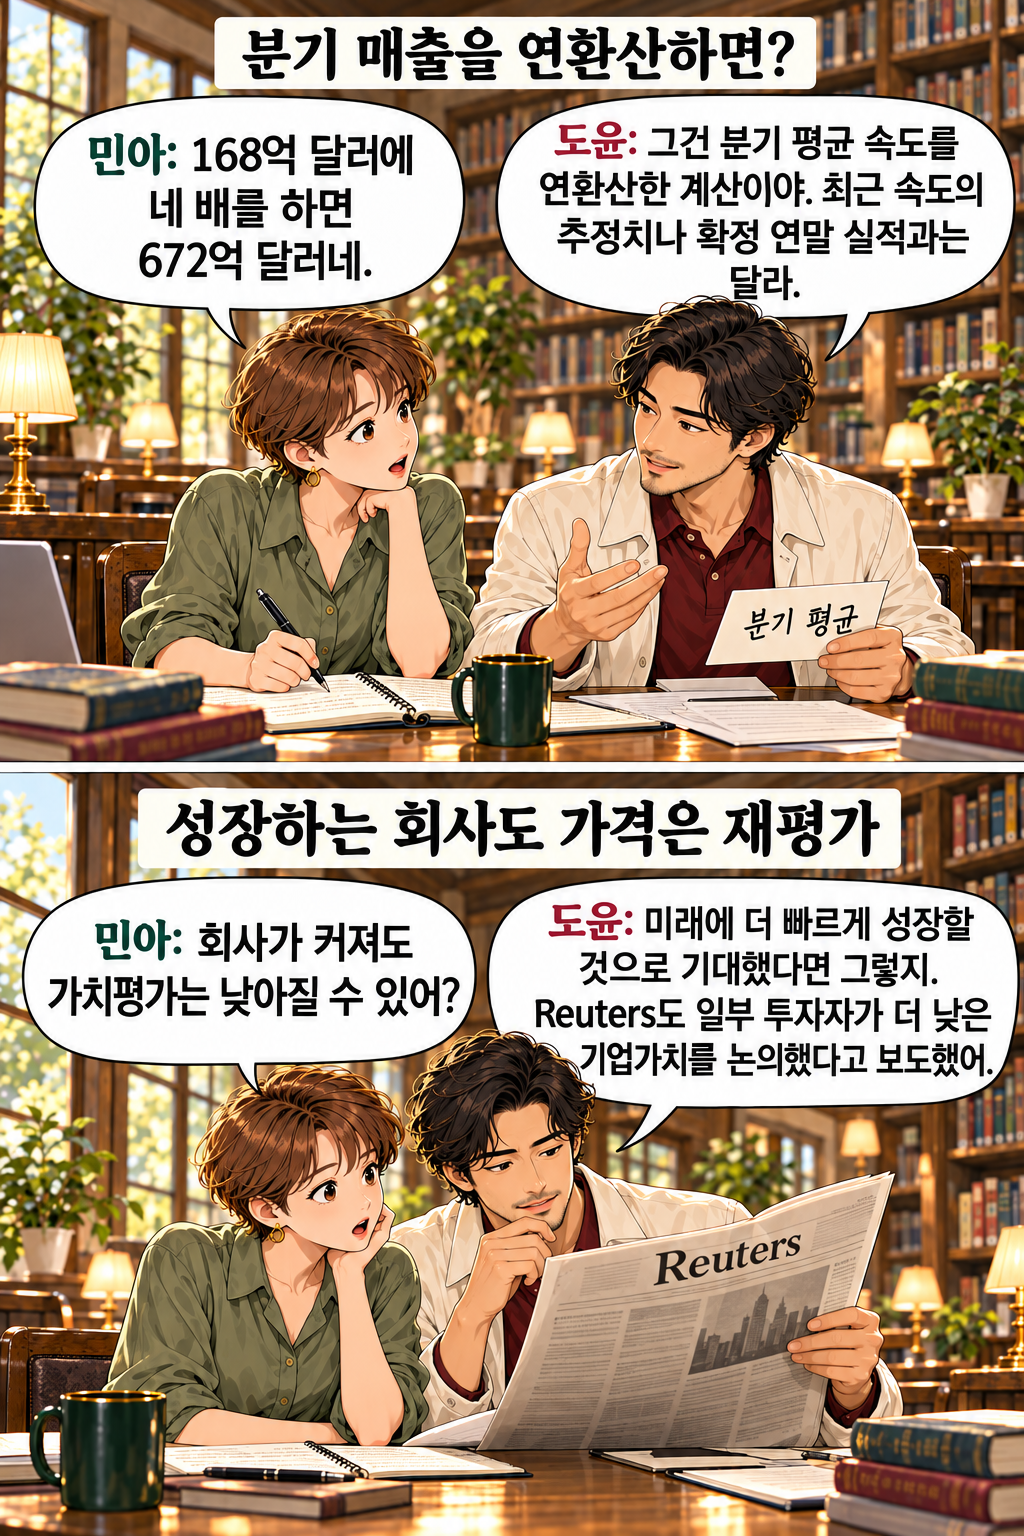
What if we annualize quarterly revenue? Mina: Multiplying 168 hundred million dollars by four gives 672 hundred million dollars. Doyun: That calculation annualizes the quarter's average pace. It differs from an estimate of the recent pace or confirmed year-end results. A growing company can still be repriced Mina: Can valuation fall even as a company grows? Doyun: Yes, if investors expected faster future growth. Reuters also reported that some investors discussed a lower valuation.
Dialogue
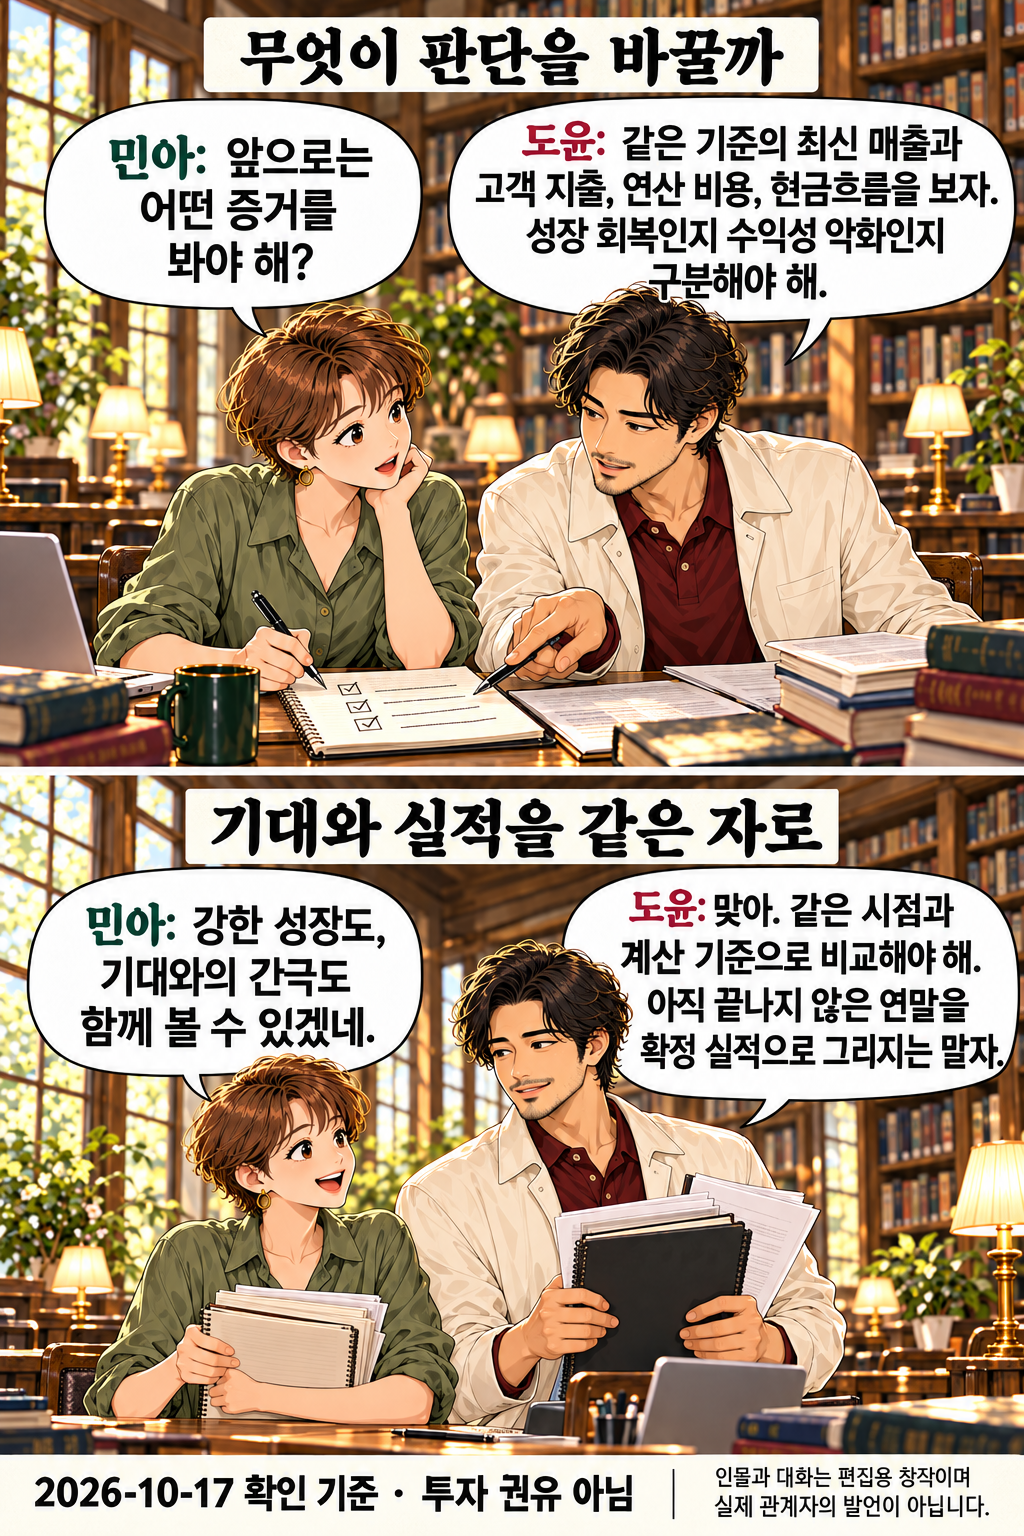
What evidence would change our judgment? Mina: What should we examine next? Doyun: Comparable latest revenue, customer spending, compute costs and cash flow. We need to distinguish a growth recovery from deteriorating profitability. Measure expectations and results with the same ruler Mina: We can acknowledge both strong growth and the gap from expectations. Doyun: Exactly. Compare the same dates and calculation methods. Let's not depict a year-end that has not arrived as confirmed results. As checked on 2026-10-17 · Not investment advice The characters and dialogue are editorial creations, not statements by actual representatives.