Distinguish ledger security from wallet and issuer responsibilities, and consider how usage connects to asset value.
Dialogue
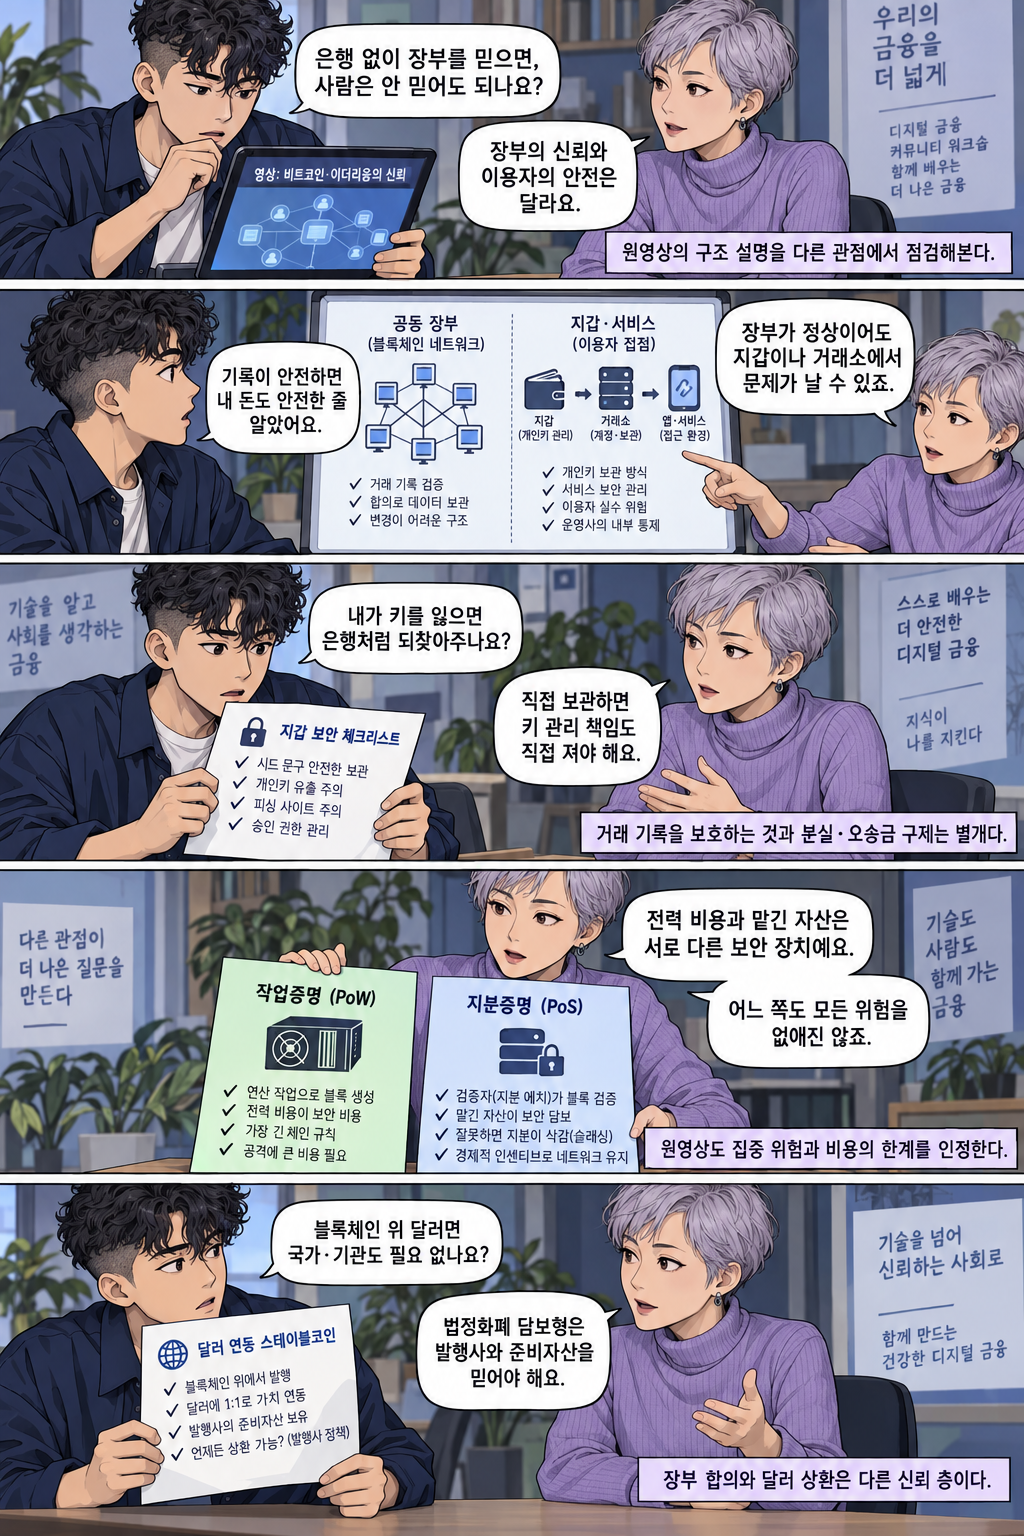
If we trust a ledger without banks, can we stop trusting people?
Trust in the ledger and user safety differ.
A working ledger does not prevent wallet or exchange problems.
I thought safe records meant safe money.
If I lose my key, will someone recover it like a bank?
Self-custody means taking responsibility for managing keys.
Protecting transaction records differs from remedies for loss or mistaken transfers.
Electricity costs and staked assets are different security mechanisms.
Neither removes every risk.
The original video also acknowledges concentration risks and cost limitations.
Do dollars on a blockchain remove the need for states and institutions?
Fiat-backed arrangements require trust in the issuer and reserve assets.
Ledger consensus and dollar redemption are different layers of trust.
Dialogue
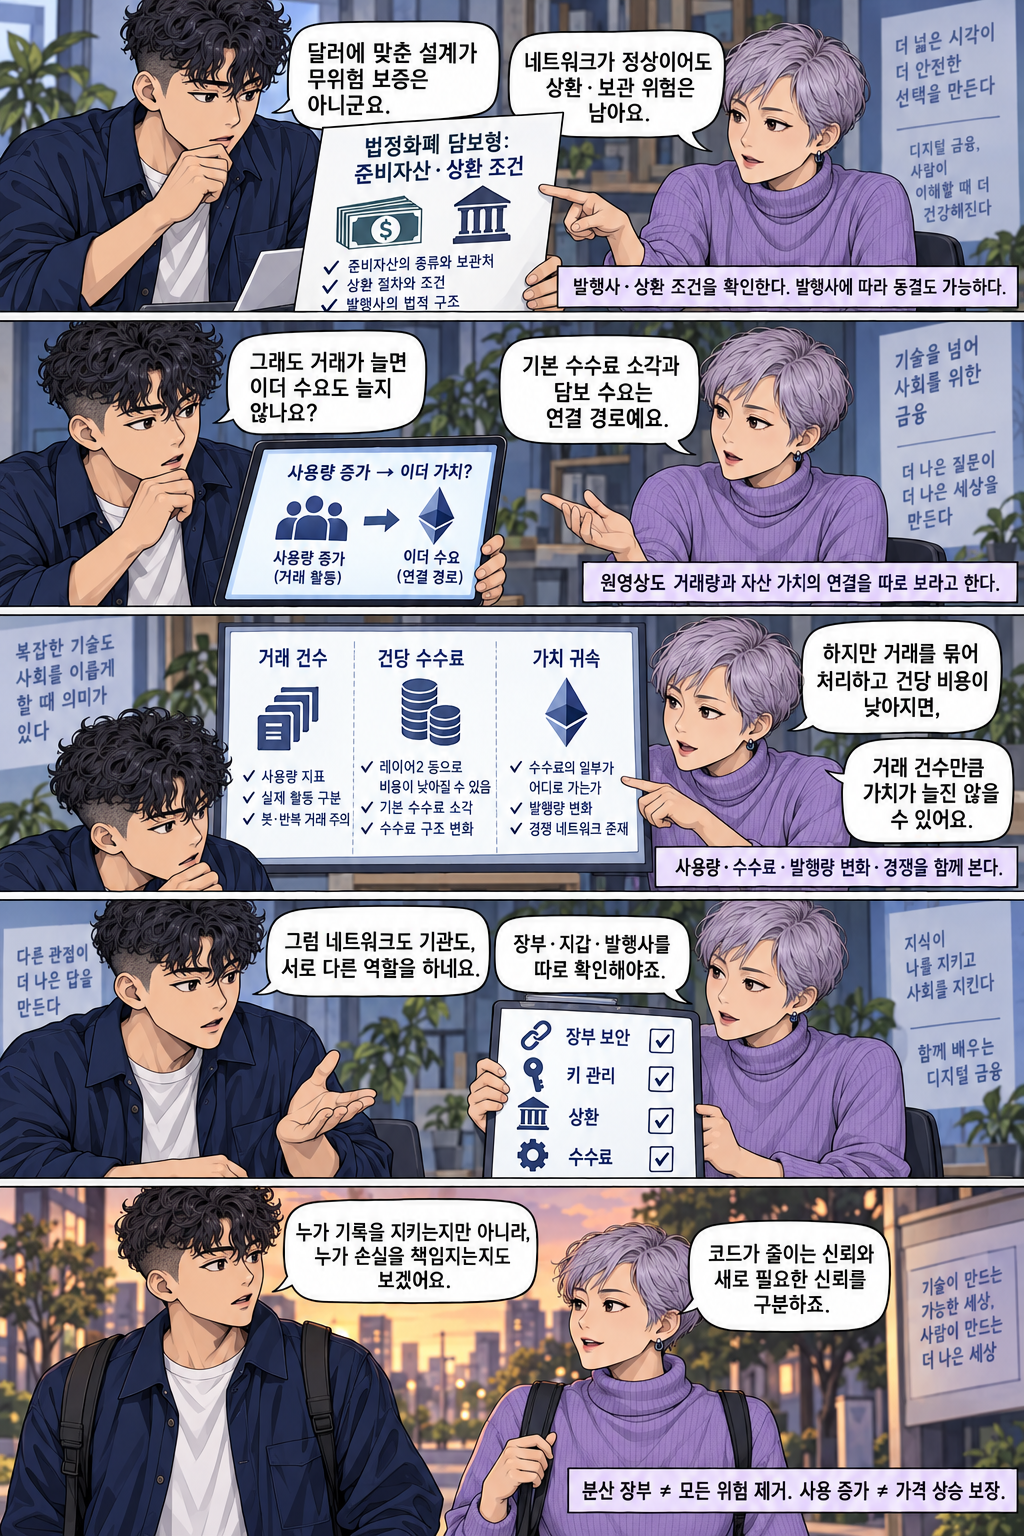
Redemption and custody risks remain even when the network works.
A design pegged to the dollar is not a risk-free guarantee.
Check issuers and redemption terms. Some issuers can freeze assets.
Still, wouldn’t more transactions mean more demand for Ether?
Base-fee burning and collateral demand are connecting channels.
The original video also says to examine transaction volume separately from asset value.
But if transactions are batched and per-transaction costs fall, value may not grow proportionally to transaction counts.
Examine usage, fees, changes in issuance, and competition together.
Then networks and institutions have different roles.
Check the ledger, wallet, and issuer separately.
I will ask not only who protects the records, but who bears responsibility for losses.
Distinguish the trust code reduces from the new trust still needed.
Distributed ledger ≠ removal of all risk. Increased use ≠ guaranteed price gains.
ASSETCASTING commentary
An interpretation of the fictional story, not a statement by the original video creator.
The original video acknowledges volatility, electricity costs, and concentration risks, and does not recommend buying. The counterargument targets interpreting shared-ledger security as removing all user risks or completely replacing trust in institutions and people. It does not distort the original video as definitively making that broader claim. Bitcoin.org material distinguishes self-custody key management from custodial-service risk. Proof-of-work and proof-of-stake descriptions are simplified concepts, not claims that all rule violations trigger automatic slashing. Issuers, reserves, and redemption conditions are described only for fiat-backed stablecoins; not all stablecoins are generalized as having that structure. This is a fictional checking scene, not an actual incident or a promise of guarantees or legal remedies.
Ethereum.org materials confirm that some issuers can block or freeze addresses, and that redemption and custody risks differ from network security. At 524–652 seconds, the original video also explains that more stablecoins do not guarantee rising Ether prices. The webtoon acknowledges connecting channels through fee burning and collateral while adding independent analysis that layer 2 batching, per-transaction costs, issuance, and competition must be examined together. It does not assert that more usage necessarily raises or lowers value. Coin prices, returns, policy adoption, or national investment amounts are not presented as predictions or verified facts; illustrated checklists and conceptual diagrams are not actual observations.